

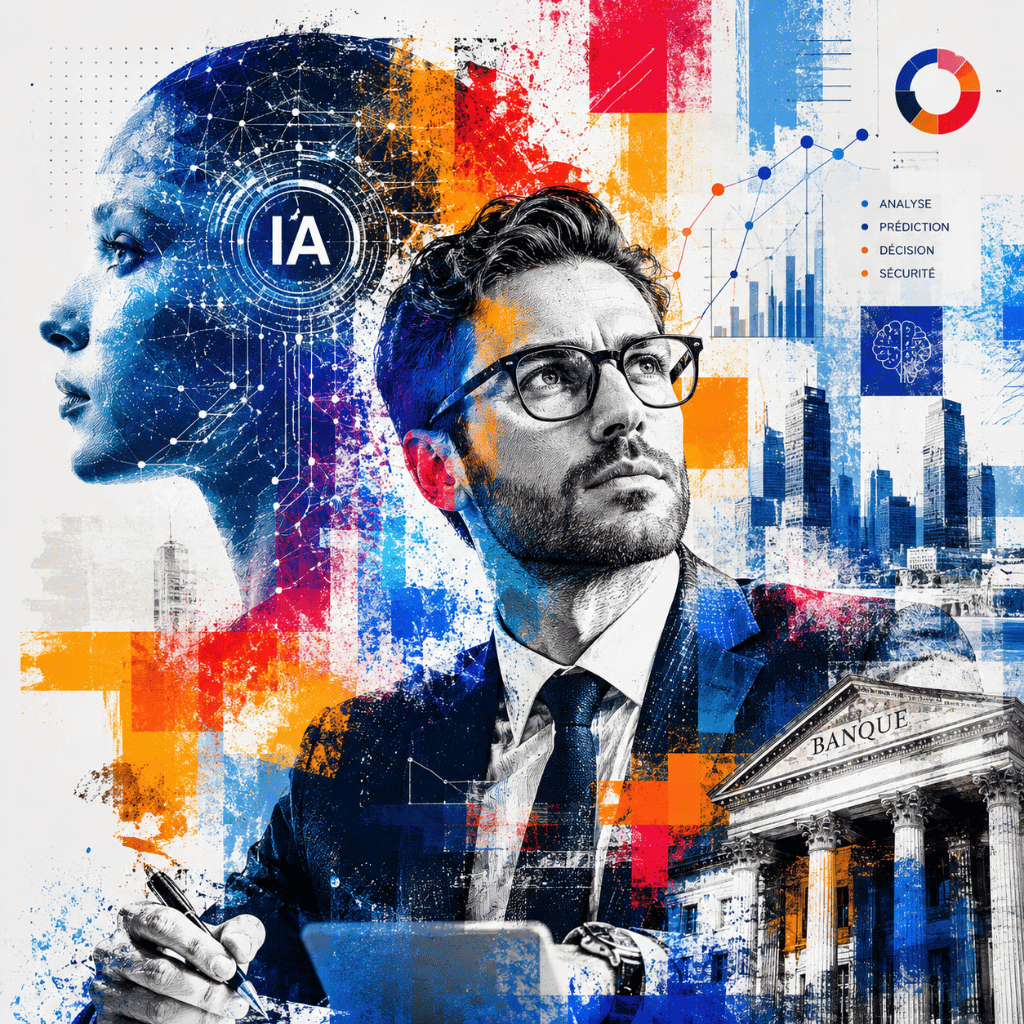
From scoring models to fraud detection systems, artificial intelligence is already present in many banking processes. Its rise, however, does not turn an algorithmic recommendation into an infallible decision. For the banker, the challenge becomes understanding what these systems actually measure, checking their limits, and preserving human accountability when decisions directly affect customers.
From traditional banking expertise to AI-assisted decisions
The banker’s role has historically relied on a combination of financial expertise, customer knowledge, risk analysis, and compliance with prudential and consumer protection rules. Depending on the position, this may involve assessing a financing application, supporting a business, managing a wealth management relationship, monitoring transactions, or contributing to compliance. Digital tools did not wait for artificial intelligence to transform banking: payment systems, rules engines, document automation, and statistical models have long been in use.
AI now adds a new layer to this infrastructure. In this article, the term covers several families of systems that must be distinguished: predictive models, used for example to estimate a risk or detect an anomaly; language processing systems, capable of extracting or classifying information; generative models, which produce text or summaries; and more agentic systems, designed to chain several tasks together using tools. These technologies do not share the same functions, the same levels of maturity, or the same risks.
Adoption has nonetheless become widespread in the European banking sector. In September 2025, the European Banking Authority (EBA) reported that 92% of the EU banks surveyed were already deploying AI use cases, while 8% were still at the pilot, testing, or discussion stage. The EBA notably cites customer and transaction profiling, customer support, fraud, anti-money laundering, credit scoring, and creditworthiness assessment.[1] This figure describes how widely these uses have spread, not their effectiveness or their level of autonomy.
The European Central Bank observes the same trend. Its supervisory work has noted growth in AI use, particularly for credit scoring and fraud detection, while stressing that the potential of generative AI is more recent and calls for specific monitoring.[2] The paradigm shift is therefore not one of a bank abandoning human judgment, but of an organization in which a growing share of the preparation, sorting, and analysis of information can be assisted by algorithmic systems.
This development requires distinguishing three levels that are often conflated: producing a score, recommending an action, and making a decision. A model can estimate a probability of default. A system can use that estimate to suggest a course of action. But the legal, commercial, or financial effect of the decision depends on the process into which that output is integrated, the applicable rules, and the actual degree of human intervention.


MSc AI & Data for Finance & Accounting
The Bac+6 AI & Data program dedicated to Finance, Accounting, Audit and Management Control careers. No programming prerequisites.
How AI is transforming banking practices
AI does not transform all banking activities in the same way. Some uses are now relatively well established, while others remain experimental or depend heavily on the quality of the institution’s data and information systems. The real novelty therefore lies not in automation itself, but in the ability of certain models to learn from data, detect patterns that are hard to formalize with simple rules, or produce content from instructions.
Credit scoring and risk assessment
Statistical and machine learning models can draw on many variables to estimate the probability of default or segment risk profiles. The ECB identifies credit among the AI use cases closely monitored by banking supervision.[2] A score nevertheless remains an estimate produced in a given context, not an absolute measure of a borrower’s future ability to repay.
Fraud detection and transaction monitoring
Systems can search for atypical patterns in large transaction flows and prioritize the alerts to be reviewed. The EBA cites fraud and anti-money laundering among the uses observed in European banks.[1] Their usefulness depends on the trade-off between sensitivity and false positives, as well as on teams’ ability to handle alerts without being overwhelmed.
Customer knowledge and personalization
Models can group customers by behavior, history, or preferences, and then support commercial segmentation. The EBA notes that profiling and clustering are among the common uses.[1] This personalization must nonetheless remain compatible with rules on personal data, non-discrimination, and consumer protection.
Document analysis and compliance
Natural language processing can help extract information from documents, prepare checks, or look for inconsistencies. In KYC and anti-money laundering processes, AI can assist with prioritization, but compliance is not just a matter of producing a score: it requires rules, traceability, and escalation procedures.
Generative AI support for advisors
Language models can prepare a case summary, rephrase an explanation, or search for information in a document base. Their main contribution is faster access to information. Their limitation is just as significant: fluent wording can contain inaccurate or fabricated information. Outputs must therefore be linked to verifiable sources and reviewed before being used with a customer.
Toward more agentic task chains
Systems can be designed to chain several actions together, for example searching for information, preparing a file, and passing a task to a business tool. In a banking environment, the central question is not only whether an agent can act, but what permissions it has, which operations require approval, and how each action is logged.
The transformation of banking work therefore plays out less as a uniform replacement of activities than as a redistribution of tasks. Highly structured operations can be further automated or pre-processed; ambiguous, sensitive, or exceptional situations, by contrast, require more context, explanation, and accountability.
A new role for the banker
Integrating AI does not turn the banker into a data scientist. It does, however, reinforce several responsibilities: understanding where a result comes from, spotting situations in which a model may be wrong, explaining a decision, and knowing when to take back control. Professional value is therefore partly shifting from executing a procedure toward interpreting and overseeing systems that prepare part of the analysis.
Interpreting without confusing score and decision
A risk score summarizes certain information according to a defined model. The banker must be able to understand what the score measures, which factors influence it, and under what circumstances it becomes unreliable. Human intervention is only meaningful if it is real, competent, and able to change the outcome when the context warrants it.
Explaining decisions to the customer
When a decision significantly affects a person, explainability goes beyond the technical. It also means being able to present the relevant factors, the avenues for appeal, and, where the framework provides for it, the options for human intervention.
Overseeing generative assistants
An advisor can use an assistant to prepare a meeting summary or a reply, but remains responsible for verifying the content sent. An error in a summary of rates, fees, risk, or contractual terms can have concrete consequences for the customer.
Contributing to the governance of AI use
Frontline professionals can identify recurring errors, biases, procedural workarounds, or situations the designers had not anticipated. This feedback is essential for adjusting models, thresholds, and escalation rules.
Preserving the relationship of trust
Algorithmic personalization does not replace an understanding of the economic or personal context. In sensitive situations, such as debt restructuring, project financing, cash flow difficulties, or wealth allocation decisions, the quality of the conversation remains a decisive component of banking service.
The banker’s new role is therefore not that of a mere operator of algorithms. It consists of integrating these tools into a practice where decisions remain justifiable, proportionate to the risk, and compatible with the institution’s obligations to its customers.
What skills does the banker need in the age of generative AI?
The fundamentals remain the priority: financial analysis, credit, customer knowledge, regulation, banking products, and risk management. AI does not reduce the need for this expertise; on the contrary, it makes it harder to evaluate an algorithmic output when the professional has not mastered the domain to which it applies.
Technical and digital skills
- Distinguishing between families of systems: a scoring model, a rules engine, an anomaly detection system, and a large language model do not serve the same function. Understanding this difference avoids attributing to generative AI capabilities that belong to other tools.
- Reading metrics with caution: precision, recall, false positive rate, calibration, or stability over time must be interpreted in light of the use case. Good average performance can mask significant gaps between customer segments.
- Checking data and sources: the quality of a result depends on the data used. Outdated data, input errors, indirectly discriminatory variables, or changes in economic behavior can reduce a model’s relevance.
- Using generative AI without automating trust: generated content should be treated as a proposal to be verified. Sensitive information should only be shared with tools authorized by the institution and compatible with its security and confidentiality rules.
Analytical and decision-making skills
- Putting a recommendation in context: a model can detect a correlation without providing the economic or personal explanation for the situation. The banker must compare the output against the relevant information in the file and the customer’s objectives.
- Recognizing uncertainty: forecasts and scores are probabilistic. Knowing how to communicate a margin of uncertainty and identify edge cases is more useful than presenting a result as a certainty.
- Knowing when to escalate: when a case is atypical, when the consequences are significant, or when the data are inconsistent, the right skill is to interrupt automation and bring in the appropriate expertise.
Ethical, legal, and organizational skills
- Understanding automated decisions under the GDPR: Article 22 of the GDPR governs decisions based solely on automated processing that produce legal effects or significantly affect a person. It provides for regulated exceptions and, in certain cases, safeguards including human intervention and the right to contest the decision.[5]
- Understanding the status of credit scoring under the AI Act: assessing the creditworthiness of natural persons or establishing their credit score is among the uses classified as high-risk by the AI Act, with exceptions including certain uses related to fraud detection. This classification entails a stricter framework for the systems concerned.[4]
- Incorporating operational resilience: DORA, applicable since January 17, 2025, requires financial entities to have an information and communication technology risk management framework. Dependencies on third-party models, infrastructure, or providers must therefore also be analyzed from a continuity and resilience perspective.[6]
- Contributing to governance: banks must be able to inventory their use cases, identify responsibilities, test systems, and track incidents. The frontline banker is not solely responsible for this governance, but becomes a stakeholder in it when using or challenging a system’s results.
Can artificial intelligence make banking decisions more reliable?
The answer depends on what we mean by “reliable.” A system can improve the detection of an event in a given context without improving every dimension of care quality. Reliability must therefore be examined on several levels: accuracy of measurement, predictive performance, quality of integration into the unit and the team’s ability to act correctly on the information produced.
What the evidence supports
Supervisory data show that European banks already use AI for credit scoring and fraud detection. The ECB confirmed an increase in these uses between 2023 and 2024 and in 2025 held workshops with thirteen banks to examine the practices concerned in more detail.[2] This establishes real adoption, but does not prove that an AI model is systematically superior to a traditional method in every context.
The EBA also describes very broad AI adoption in the European banking sector and highlights both potential benefits in terms of efficiency and risk management and challenges related to privacy, cybersecurity, compliance, and technological dependencies.[1] Results must therefore be evaluated use case by use case, on representative data, and under conditions close to real-world operation.
Credit is a particularly clear illustration of this requirement. In France, the CNIL published a recommendation on credit granting in May 2026, reiterating that Article 22 of the GDPR applies when automated creditworthiness assessment leads to an approval or rejection without meaningful human intervention.[7] The question is therefore not only whether the score is accurate, but how it is used in the decision-making chain.
Limitations to watch
- False positives and false negatives: in fraud detection, an overly sensitive system can flood teams with alerts on legitimate activity; an overly permissive system can let fraudulent transactions through. The choice of threshold reflects an operational trade-off that must be explicitly governed.
- Bias and discrimination: seemingly neutral variables can be correlated with protected characteristics or reproduce historical inequalities. Acceptable overall performance is not enough: gaps between groups and segments must be investigated and documented.
- Model drift: economic behavior, fraud, and customer profiles evolve. A model that performs well when deployed can lose relevance if the data change. Ongoing monitoring therefore becomes as important as initial validation.
- Opacity and contestability: when a result strongly affects a customer, a decision that is hard to explain undermines the ability to contest it and trust in the process. The AI Act notably requires a level of transparency that enables deployers to understand and correctly use the outputs of high-risk systems.4
- Generative AI hallucinations: an assistant can invent a figure, a rule, or a justification. This limitation makes it particularly risky to use generated text as the sole basis for financial advice, a compliance decision, or a contractual communication.
- Operational risk and vendor dependency: an outage, a model change, or an incident at a service provider can affect the banking process. DORA specifically strengthens the management of ICT and third-party risks in financial entities.6
AI can therefore improve certain banking processes when it is properly designed, validated, and integrated. It does not make a decision reliable by nature. Reliability comes from the complete sociotechnical system: data, model, business rules, human oversight, security, customer recourse, and governance.
What will the banker’s job look like tomorrow with AI?
It would be premature to describe a single model of the “banker of tomorrow.” Uses differ across retail banking, corporate banking, wealth management, risk functions, compliance, and operations. Institutions also do not have the same infrastructure, data, or levels of maturity. Several trends are nonetheless visible enough to be examined without presenting them as certainties.
- More assisted case preparation: systems will be able to aggregate information, flag inconsistencies, and prepare summaries. The time saved will only translate into better advice if the organization actually reallocates that time to analysis and dialogue with the customer.
- More continuous risk monitoring: fraud, transaction anomalies, and changes in certain indicators will be tracked more frequently. This monitoring also increases the volume of alerts and therefore requires prioritization and control mechanisms.
- Generative assistants more present in customer relationships: they will be able to facilitate document searches or prepare replies. Their deployment will require well-controlled knowledge bases, confidentiality controls, and a precise definition of the situations in which a human must take back control.
- Agentic systems within controlled boundaries: some assistants will be able to chain several tasks together. In sensitive processes, the key question will be the rights granted to the system: reading, proposing, forwarding, modifying, or executing are not equivalent levels of autonomy.
- More structured AI governance: the ECB has included AI strategy, governance, and risk management among its supervisory topics. It notably plans to continue targeted monitoring of banks’ generative AI applications.8
- Greater need for regulatory understanding: bankers will have to work in an environment where banking regulation, data protection, digital resilience, and the AI Act overlap. Not all AI systems will be subject to the same requirements; the use case, purpose, and level of impact will remain decisive.
The effects of automation on learning the profession will also need to be monitored. If systems take over the analysis of simple cases too early, junior professionals may have fewer opportunities to understand how credit reasoning, risk analysis, or a relationship of trust is built. Automating a task therefore does not remove the need to organize the transfer of the skills it used to help develop.
The future of the profession will depend less on a replacement scenario than on how institutions divide responsibilities between tools and professionals. The more the system prepares and recommends, the more necessary it becomes to define who verifies, who explains, who can override, and who owns the final decision.
AI-augmented banking, built on trust that remains human
Artificial intelligence can speed up data analysis, spot atypical patterns, and produce summaries. It does not, however, bear the economic consequences of a credit refusal, an institution’s regulatory responsibility, or the relationship of trust with a customer. These responsibilities remain with people and organizations.
Responsible use therefore requires a clear purpose, appropriate data, performance measured in a relevant context, sufficient traceability, and avenues for human intervention when the consequences demand it. This requirement is particularly strong when the technology is involved in access to credit, an area the AI Act considers sensitive for fundamental rights.[4]
For bankers, the most important transformation may be less spectacular than full automation. It lies in the ability to work with systems that provide more information and recommendations, while retaining enough critical thinking to detect their limits. The profession may thus shift toward more explanation, contextualization, and judgment.
Technology can produce a score in a few seconds. It can also create an illusion of certainty. The banker’s role remains knowing what that score means, what it does not mean, and what consequences may follow from its use.
The question to watch is therefore less “Will AI decide in place of the banker?” than this one: will banks be able to use automation to improve the quality of their decisions without weakening explainability, customer recourse, and human accountability?
Further reading
To take this discussion of AI in finance, decision governance, and evolving skills further, here are four complementary reads from the aivancity blog.
Sources
[1] European Banking Authority. (2025). Rising Application of AI in EU Banking and Payments Sector. View report
[2] European Central Bank, Banking Supervision. (2025). AI’s Impact on Banking: Use Cases for Credit Scoring and Fraud Detection. View source
[3] European Banking Authority. (2025). Special Topic: Artificial Intelligence. View publication
[4] European Union. (2024). Règlement (UE) 2024/1689 établissant des règles harmonisées concernant l’intelligence artificielle (AI Act), in particular Article 6 and Annex III. View regulation
[5] European Union. (2016). Règlement (UE) 2016/679, article 22 : Décision individuelle automatisée, y compris le profilage. View regulation
[6] European Union. (2022). Règlement (UE) 2022/2554 sur la résilience opérationnelle numérique du secteur financier (DORA). View regulation
[7] CNIL. (2026). Recommandation relative aux traitements de données à caractère personnel mis en œuvre aux fins d’octroi de crédit. View recommendation
[8] European Central Bank, Banking Supervision. (2025). Supervisory Priorities 2026-2028. View priorities