

The rise of artificial intelligence is driving up demand for semiconductors and computing infrastructure. Yet manufacturing and cooling them still rely on fluorinated substances, some of which belong to the vast family of PFAS. An investigation by ChemSec, reported by The Guardian, indicates that several major producers plan to expand their capacity, citing in particular the needs of chips and data centers. This signal reignites a complex debate: how can chemical persistence and emissions be reduced without ignoring the technical functions for which alternatives remain difficult to qualify?
What Just Happened
On September 14, 2026, The Guardian reported the findings of a ChemSec investigation into the world’s ten largest PFAS producers. According to the nongovernmental organization, almost all of them plan to increase their production or capacity. In company communications, several investments are linked to demand from semiconductors, batteries, cables, cooling and data centers.[1][2]
Two examples illustrate this trend. In June, Arkema announced a 15% increase in its US capacity for PVDF, a fluoropolymer intended in particular for semiconductors and data center expansion. In August, Chemours launched two refrigerants for stationary chillers and data centers, highlighting their low global warming potential.[5][6]
These announcements do not, however, show that AI is the sole cause of a global resurgence in PFAS. The same materials are used in electronics, automotive, energy, healthcare and many industrial processes. The most robust finding is narrower: the expansion of AI infrastructure is now one of the commercial arguments used to justify new capacity for fluorinated substances.
Why AI is involved without being the only cause
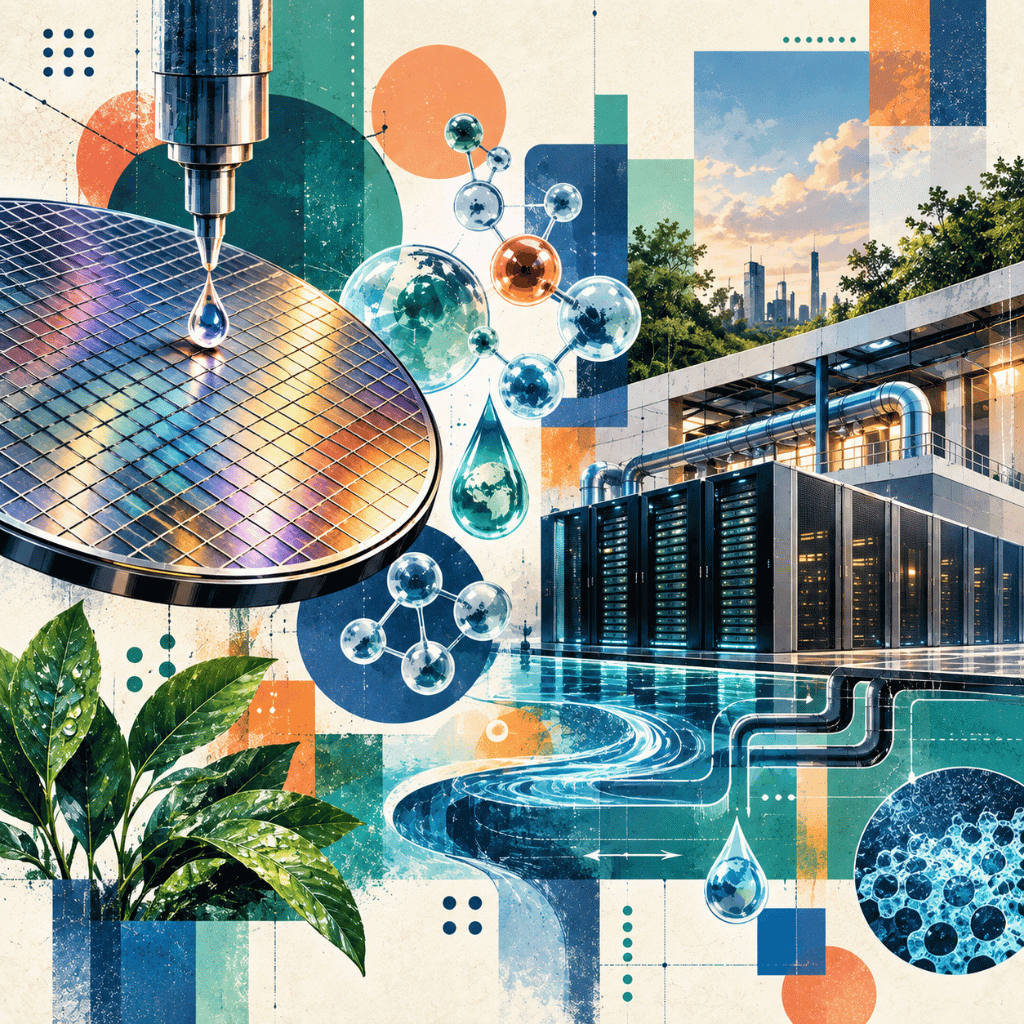
Large models require accelerators, high-bandwidth networks, memory and cooling systems. As operators build more specialized data centers, demand moves up the entire value chain: extraction and purification of materials, wafer fabrication, photolithography, etching, assembly, cabling and thermal management.
AI’s chemical footprint therefore exists at two levels. It is indirect in the semiconductor fabs that produce the components. It can be more direct in cooling equipment and loops, cables, seals and certain data center fluids. This footprint is less visible than electricity, water or carbon, because operators rarely publish substance inventories that can be compared across sites.
The term PFAS also refers to a very broad family of per- and polyfluoroalkyl substances. Their structure, mobility, toxicity, uses and legal status can differ. Talking about PFAS as if they were a single product therefore leads to overly general conclusions. Conversely, their shared high persistence justifies a family-based approach and particular attention to emissions across the entire life cycle.[3][8]
Where fluorinated substances come into play
| Use | Technical function | Point of concern |
|---|---|---|
| Photolithography | Photoacid generators and surfactants used to form very fine patterns on wafers. | Substances used in small quantities but in demanding processes, with alternatives that are difficult to qualify quickly. |
| Plasma etching and deposition | Fluorinated gases used to etch layers or clean process chambers. | Some may not be destroyed. However, fluorinated greenhouse gases and PFAS should not automatically be conflated. |
| Wet chemistry | Wetting agents, filtration and surface treatments needed for high purity. | Risk of transfer to effluents if capture, destruction and monitoring are insufficient. |
| Heat transfer | Fluids and materials that withstand heat, electrical stress and harsh conditions. | Possible leaks, complex end-of-life management and a lack of public data on the volumes actually used. |
| Cables, seals and components | Fluoropolymers providing insulation, chemical resistance and durability. | Emissions can occur mainly during manufacturing, fires, waste treatment or end of life. |
The technical inventory published by the Semiconductor Industry Association’s PFAS Consortium confirms this diversity of uses. It is, however, an industry source, produced by companies affected by the proposed restriction. It usefully documents functions and substitution constraints, but does not constitute an independent assessment of their impacts.[3]
What the investigation actually allows us to say
| Available evidence | What it supports | What it does not prove |
|---|---|---|
| ChemSec survey of ten producers | Most of the companies studied are announcing expansions, investments, or capacity increases. | It does not measure additional tonnages attributable exclusively to AI. |
| Arkema and Chemours announcements | Semiconductors and data centers are among the explicitly targeted markets. | They do not show that all the products mentioned have the same hazard profile or the same regulatory status. |
| Chip industry inventories | Fluorinated substances fulfill several critical functions in production. | They do not provide public, harmonized accounting of releases per chip or per AI model. |
| Growth of liquid cooling | Compute density is increasing interest in new thermal architectures. | It does not imply that all liquid cooling uses PFAS. |
ChemSec is an advocacy organization that campaigns for the replacement of hazardous substances. Its investigation is a relevant source for identifying industrial strategies, but its interpretation must be weighed against company announcements, regulatory data, and environmental measurements. The Guardian adds journalistic work to this, without resolving the main blind spot: the absence of a global public assessment linking production volumes, end uses, and emissions attributable to AI.[1][2]


MSc Data Engineering
& Cloud Computing
Master the full data engineering and cloud lifecycle (AWS, Azure). RNCP Level 7 certification (Bac+5/6).
Low climate impact does not mean no persistence
In cooling, manufacturers often highlight the global warming potential, or GWP, of fluids. This indicator estimates their contribution to climate change relative to carbon dioxide. Reducing GWP is useful, but it does not automatically address questions of persistence, degradation products, ecotoxicity, or water contamination.
The two refrigerants announced by Chemours illustrate this distinction. The company reports a GWP of about 1 for Opteon ZE and about 293 for Opteon 515B, well below some legacy fluids. This claimed climate performance is not, by itself, enough to determine their full environmental footprint or whether they qualify as PFAS under the regulatory definitions adopted.[6]
A distinction must also be made between direct cooling with dielectric fluid, water loops, chillers using a refrigerant, and air cooling. Not all data centers, therefore, involve the same substances, the same exposure pathways, or the same leak risks.
Why substitution remains difficult
Chip manufacturing combines temperature, vacuum, plasma, corrosiveness, extreme purity, and nanometer-scale dimensions. Substitution is not just a matter of finding a molecule with a similar function. It must preserve production yield, component reliability, operator safety, and compatibility with equipment that has already been qualified.
The validation cycle can be long, because a minimal change can introduce defects or shorten a component’s lifespan. Manufacturers therefore argue for temporary exemptions when no solution is available at the required scale. This technical constraint is real, but it does not exempt them from establishing substitution plans, deadlines, release measurements, and documented proof that each use is essential.
A responsible approach combines three priorities: eliminating non-essential uses for which an alternative exists, containing and treating emissions from uses that are still indispensable, and investing in less persistent processes and materials. The question is not choosing between digital innovation and environmental protection, but integrating the chemical cost into architecture and procurement decisions.
Health and environmental risks: what we know
Persistence is the most worrying common feature: many PFAS degrade very slowly and can accumulate in the environment. Some well-studied substances have been associated with health effects, notably on the immune system, development, metabolism, and certain cancers. These findings cannot be applied uniformly to every member of the family, but they justify prevention, monitoring, and exposure reduction.[7][8]
For semiconductors, the relevant pathways include air emissions, process water, sludge, waste, and incidents. For data centers, they include upstream manufacturing, fluid leaks, maintenance, fires, and end-of-life equipment. The risk therefore depends as much on the properties of the substance as on the quantity, containment, and exposure.
To date, public data do not make it possible to establish a robust inventory of PFAS consumed or released by AI data centers alone. This limitation must be made explicit: it prevents a precise quantification of AI’s share, but it does not justify waiting before improving traceability.


MSc AI Governance, Risk & Compliance
The Bac+6 program that trains legal professionals to understand AI and data technologies in order to master their governance, risks, and compliance.
In Europe, regulation still under construction
The European Union already regulates several PFAS, including PFOS and PFOA, through various legal texts. In parallel, five countries submitted a much broader restriction proposal under REACH in 2023. The European Chemicals Agency is continuing its scientific assessment of uses, derogations, and socioeconomic consequences. As of September 22, 2026, this general proposal does not constitute a uniform ban already in force.[7]
The debate focuses in particular on the definition of scope, essential uses, the availability of alternatives, and the length of transition periods. Semiconductors are among the sectors where technical functions and qualification timelines are being closely examined. The outcome may combine bans, limitations, control obligations, and temporary exemptions rather than an identical rule for all uses.
For digital companies, waiting for the final text would be risky. Supply contracts, site design, and equipment have long cycles. Mapping substances now makes it possible to prepare for compliance, limit pollution liabilities, and avoid the late replacement of a material that has become hard to obtain.
What responsible governance should measure
- An inventory of PFAS and other fluorinated substances by site, equipment, supplier, and life-cycle stage.
- Quantities purchased, contained, lost, recovered, destroyed, and transferred to waste or effluents.
- The distinction between direct data center emissions and the upstream footprint linked to manufacturing chips, cables, and thermal systems.
- Criteria for selecting alternatives, covering climate, persistence, toxicity, safety, and technical performance.
- Supplier clauses on composition, analytical methods, incidents, end of life, and substitution timelines.
- Verifiable public disclosure, with scope, methodology, uncertainties, and year-over-year trends.
This governance is a matter of compliance, ethics, and industrial strategy alike. It protects workers and local residents, reduces the financial risks associated with remediation, and helps buyers compare solutions. It also prevents a local energy gain, such as more efficient cooling, from masking a shift of impact toward chemistry or end of life.
What to Watch Next
Three developments will be decisive. The first concerns the publication of data: volumes per use, measured emissions, and treatment methods. The second involves truly qualified alternatives, their industrial availability, and their full footprint. The third will be regulatory, with the continuation of the European assessment and decisions taken in other jurisdictions.
It will also be necessary to follow how AI operators integrate these substances into their environmental targets. Sustainability reports often detail energy, water, and carbon, but much less the chemistry of infrastructure. Credible accounting for responsible AI will have to link these dimensions instead of treating them separately.
ChemSec’s investigation therefore does not allow us to conclude that AI alone would trigger a new global wave of PFAS. It nonetheless reveals a concrete tension: the growth of computing still relies on materials whose environmental persistence can far exceed the lifespan of the equipment. Making this dependence visible is the first step toward reducing it.
Further reading
To place this chemical footprint in the context of AI’s environmental, industrial, and infrastructure transformations, also explore these analyses from the aivancity blog.
Sources
[1] The Guardian, September 14, 2026. PFAS firms ride AI demand as campaigners warn of new wave of forever chemicals. View source
[2] ChemSec, 2026. The world’s top 10 PFAS producers, most are expanding production. View source
[3] Semiconductor Industry Association, PFAS Consortium. PFAS uses in semiconductor manufacturing. Accessed September 22, 2026. View source
[4] US Environmental Protection Agency. Semiconductor Industry: processes and fluorinated compounds. Accessed September 22, 2026. View source
[5] Arkema, June 23, 2026. Arkema successfully started its PVDF capacity expansion in the United States. View source
[6] Chemours, August 10, 2026. Chemours launches Opteon ZE and Opteon 515B refrigerants. View source
[7] European Chemicals Agency (ECHA). PFAS and the proposed restriction under REACH. Accessed September 22, 2026. View source
[8] OECD, 2021. Reconciling Terminology of the Universe of Per- and Polyfluoroalkyl Substances. View source